Main Facts
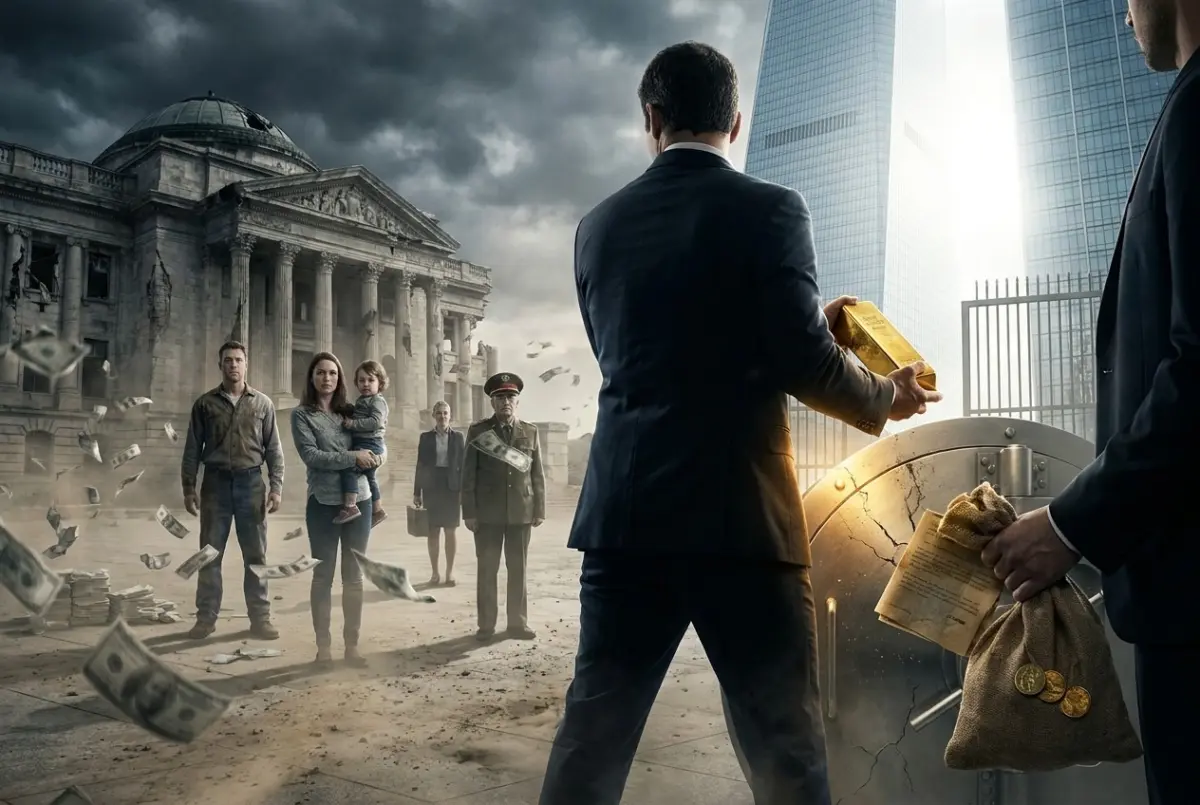
The United States is currently navigating what financial analysts and independent researchers describe as the terminal phase of dollar hegemony and modern empire: a systematic, insider-driven extraction of real wealth. According to long-standing critiques from alternative economic commentators and institutional observers, the divergence between the politically connected class and ordinary citizens has reached a critical tipping point. This K-shaped economic environment—characterized by speculative asset inflation for the wealthy and rising debt, inflation, and stagnant purchasing power for the working class—is no longer viewed as a cyclical market correction. Instead, critics argue it is the intended outcome of decades of monetary engineering and centralized fiscal policy.
Central to this final extraction phase is the weaponization of asymmetrical information. Politically connected actors, leveraging early access to public policy shifts and macroeconomic announcements, routinely front-run the general public. Recent market anomalies, such as the alleged front-running of .si domain names following high-profile artificial intelligence infrastructure announcements, highlight how localized administrative actions are allegedly exploited for private windfall gains. While major stock indexes and select asset classes have historically drifted upward, underlying indicators—such as the multi-decade compression of the national savings rate and the insolvency of central bank balance sheets on a mark-to-market basis—suggest the broader economic foundation is severely compromised.
With precious metals showing historic strength—spot gold trading near $4,170 per ounce and silver approaching $61 per ounce—independent financial strategists argue that smart money is rapidly exiting fiat currency instruments. Concurrently, the commercial and residential real estate sectors face mounting headwinds. As borrowing costs hover near 7.5% to 8%, home equity values face severe downside pressure, threatening the primary reservoir of middle-class savings. The confluence of unbacked fiat creation, escalating sovereign debt, and asymmetric information access has transformed the American economic landscape into a high-stakes arena where the protected elite cash out, leaving ordinary citizens to shoulder the cost of currency devaluation.
Chronology of the Modern Economic Divergence
The structural mechanics leading to the current financial environment span several distinct historical phases of monetary policy and legislative action:
- 1971 (The Fiat Turning Point): The unilateral suspension of the U.S. dollar’s convertibility into gold by the Nixon administration removed the final external discipline on federal spending and central bank money creation, inaugurating the modern unbacked fiat era.
- The 2008 Financial Crisis and Quantitative Easing: Following the subprime mortgage collapse, the Federal Reserve implemented large-scale asset purchases (Quantitative Easing). This policy injected trillions of newly created dollars into the financial system, disproportionately inflating asset prices for financial institutions and equity holders while failing to trickle down productively to Main Street.
- The 2020–2022 Pandemic Response: Emergency fiscal stimulus and monetary expansion during the COVID-19 pandemic accelerated the divergence. Beneficiaries across the tech, biopharmaceutical, and defense sectors consolidated centralized technocratic control, while supply chain disruptions and money printing ignited the most severe inflationary cycle in four decades.
- 2023–2025 (The Debt Ceiling and Interest Rate Shock): As national debt surpassed $35 trillion and central banks aggressively hiked interest rates to combat inflation, borrowing costs surged across commercial and consumer sectors. The rapid transition from ultra-low interest rates to restrictive monetary policy exposed deep vulnerabilities in regional banking, commercial real estate, and consumer credit.
- Present Day (The Final Extraction): Insiders utilize early administrative intelligence regarding emerging technologies, such as advanced artificial intelligence initiatives and infrastructure deregulation, to execute high-conviction speculative plays. Simultaneously, retail investors face eroding purchasing power and compressed savings rates.
Supporting Data and Economic Indicators
A rigorous examination of macroeconomic metrics reveals deep systemic stress beneath surface-level headline economic data:
- National Savings Rate Collapse: Over the past three decades, the U.S. national savings rate has experienced a dramatic structural decline. Economists pointing to this trend argue that persistent low-interest-rate regimes and continuous monetary expansion have disincentivized saving while rewarding reckless leverage and asset speculation.
- Precious Metals Valuation: Gold prices near $4,170 per ounce and silver trading around $61 per ounce reflect deep-seated institutional and retail hedging against counterparty risk. Unlike fiat currency, which is subject to unlimited creation by central authority decree, precious metals maintain intrinsic purchasing power independent of government solvency.
- Real Estate Vulnerability: Mortgage rates persistently testing the 7% to 8% threshold have paralyzed residential turnover and initiated downward pricing corrections in overvalued metropolitan markets. Because home equity represents the primary vehicle for middle-class wealth accumulation in America, valuation drawdowns threaten widespread household insolvency.
- Federal Reserve Balance Sheet Stress: According to mark-to-market valuations highlighted by financial analysts, the Federal Reserve holds substantial unrealized losses on its portfolio of long-term Treasury bonds and mortgage-backed securities purchased during eras of lower interest rates. This dynamic places strict limitations on the central bank’s capacity to intervene in future liquidity crises without triggering hyperinflationary spirals.
Official Responses and Institutional Perspectives
Establishment institutions, including the Federal Reserve, the U.S. Department of the Treasury, and major Wall Street banking entities, maintain that current monetary policies are necessary tools for stabilizing employment and managing inflation targets.
Official communications from central bankers routinely characterize inflation spikes as "transitory" or driven by exogenous geopolitical shocks rather than domestic monetary expansion. Regulatory bodies contend that markets remain fundamentally sound, pointing to robust corporate earnings among large-cap technology firms and low headline unemployment rates as evidence of economic resilience. Furthermore, federal regulators argue that structural oversight mechanisms are fully adequate to prevent systemic insider trading and front-running in emerging technology sectors.
Conversely, independent economists, free-market think tanks, and monetary historians view these official assurances as obfuscation. Critics argue that mainstream economic models rely on circular logic designed to mask the redistributive effects of central bank policy. By framing systemic wealth transfer as natural market evolution, institutional defenders deflect accountability for the widening wealth gap, eroding middle-class stability, and the long-term degradation of the U.S. dollar’s global reserve status.
Implications for the Future
The convergence of unchecked sovereign debt, asymmetric insider enrichment, and currency debasement carries profound implications for the socio-economic structure of the United States and the stability of the global financial order.
1. The Threat of Hyperinflationary Pressures
As the federal government continues to run structural deficits requiring the monetization of sovereign debt, the purchasing power of the U.S. dollar faces an accelerating downward trajectory. Independent analysts warn that without drastic fiscal reform—an outcome politically unviable in the near term—the nation risks drifting toward severe currency depreciation reminiscent of historical hyperinflationary episodes.
2. The Systematic Erasure of the Middle Class
The combination of persistent inflation, elevated borrowing costs, and deflating asset values threatens to permanently transition the United States from a property-owning society to a rentier economy. When home equity vanishes and wages fail to keep pace with the true cost of living, the productive middle class is stripped of its economic agency, fulfilling the K-shaped divergence where only the connected elite retain capital.
3. The Rise of Decentralized and Self-Reliant Alternatives
In response to the perceived failure of centralized financial and informational institutions, a growing counter-economy is taking shape. Individuals and communities are increasingly turning toward decentralized assets, honest money (gold and silver), local agricultural independence, and open-source technological tools. Platforms championing free speech, uncensored artificial intelligence, and peer-to-peer networks are proliferating as digital bastions against top-down technocratic control.
Summary
The transition into the final extraction phase signals that passive financial strategies are no longer viable for ordinary citizens. Navigating the unfolding economic environment requires a decisive shift toward tangible assets, absolute debt reduction, and active participation in decentralized, resilient local infrastructures. Those who recognize the structural realities of modern fiat economics and adapt accordingly will retain their autonomy, while those anchored to legacy systems risk bearing the ultimate cost of the collapse.