By Global Housing & Lifestyle Desk
For generations, the American Dream has been packaged as a neat, universally understood ideal: graduate school, secure a stable career, fall in love, and buy a home with a white picket fence. Homeownership has long served as the ultimate rite of passage into adulthood—a tangible symbol of financial maturity, civic contribution, and personal independence.
Yet, for millions of young adults navigating the modern landscape, that dream feels increasingly like a relic of a bygone era. Over the past five years, the global and domestic housing markets have stagnated into a formidable fortress. A severe lack of housing inventory, stubbornly high mortgage rates, and skyrocketing property values have converged to create an unprecedented affordability crisis. Consequently, younger generations are renting at historical rates. According to data from the National Association of Realtors, the median age of a first-time homebuyer in the United States is projected to hit 40 by 2026—a striking milestone that highlights just how far out of reach traditional milestones have drifted.
As society shifts from an ownership culture to a perpetual rental economy, experts are asking a fundamental question: Does owning a home actually make you happier? And conversely, what are the hidden psychological and biological tolls of a lifetime spent renting?
Recent sociological, psychological, and biological research reveals a complex reality—one that challenges our deeply ingrained assumptions about property, peace of mind, and the true foundations of a well-lived life.
Main Facts: The Modern Housing Crisis and the Myth of Automatic Happiness
At first glance, the data seems to validate the traditional obsession with buying property. Homeowners consistently report being significantly more satisfied with their living situations than renters, and crucially, that satisfaction does not appear to fade over time. A prominent long-term study conducted in Germany by researchers Clark and Diaz-Serrano (2021) discovered that individuals who transition into homeownership maintain an elevated appreciation for their housing, with little to no erosion of that satisfaction even after five years.
However, a critical nuance emerges when researchers decouple housing satisfaction from life satisfaction. A separate German longitudinal study tracking participants over extended periods found that while buying a home instantly boosts how people feel about their physical four walls, it has virtually no lasting, direct effect on their overall life satisfaction (Will & Renz, 2024).
The culprit behind this discrepancy is almost universally financial: the mortgage. The psychological burden and monthly strain of servicing a massive home loan frequently depress an individual’s overall life satisfaction enough to completely cancel out the psychological benefits of holding the deed.
Further expanding on this dynamic, a comprehensive international study utilizing datasets from the U.S., the U.K., and Australia revealed that the vaunted "homeowners are happier" gap is driven almost entirely by individuals who own their properties outright (Clark et al., 2025). For homeowners saddled with hefty mortgages and minimal equity, that psychological advantage largely evaporates, leaving them questioning whether the financial stretch was truly worth the peace of mind.
Chronology: The Evolution of the Rent Versus Buy Dilemma
To understand how we arrived at an era where a 40-year-old first-time homebuyer is the new normal, it is vital to trace the historical and systemic shifts in housing over recent decades.
- The Post-War Era to the Early 2000s: Homeownership was heavily subsidized and prioritized as a wealth-building engine for the middle class. Low interest rates and abundant suburban expansion made buying a accessible target for individuals in their mid-to-late twenties.
- The 2008 Financial Crisis: The subprime mortgage meltdown upended the housing market, leading to mass foreclosures and a sudden cultural shift. A generation of young adults watched their parents lose equity, laying the groundwork for a more cautious, skeptical view of property acquisition.
- The Mid-2010s Recovery and Urbanization: As markets recovered, urbanization surged. Renting urban apartments became a lifestyle choice emphasizing flexibility over stability, particularly for millennials prioritizing career mobility over long-term roots.
- The Post-Pandemic Shock (2020–2025): COVID-19 unleashed a frantic housing rush driven by historic lows in interest rates, which was immediately followed by aggressive monetary tightening. Central banks raised interest rates to combat inflation, pushing mortgage rates to multi-decade highs. Supply chains stalled, building costs surged, and housing inventory vanished.
- The Present Era (2025–2026): Homeownership has transformed from a standard milestone into a luxury good. With the median first-time buyer age climbing to 40, renting has evolved from a transitional phase into a long-term, sometimes permanent, lifestyle reality for tens of millions of adults.
Supporting Data: The Psychological and Biological Toll of Renting
While the financial debate over renting versus buying is fierce, the psychological and biological data paints an even more striking picture of how our living arrangements shape our bodies and minds.
Loneliness and Social Capital
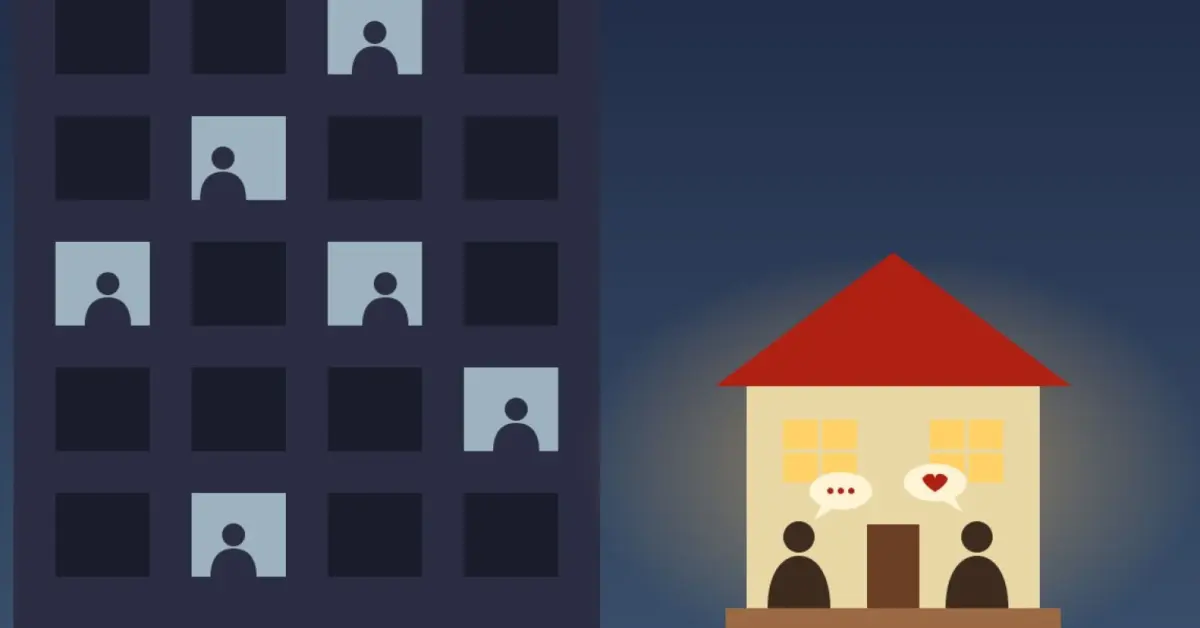
A massive poll of over 10,000 adults in the U.K. conducted by the Belonging Forum (2024) highlighted a stark divide in social well-being between tenures. Approximately 40 percent of renters reported chronic feelings of loneliness, compared to only 29 percent of people who owned their homes outright.
Furthermore, social connectivity showed deep disparities:
- Knowing Neighbors: 69 percent of outright homeowners knew their neighbors well, compared to just 43 percent of renters.
- Friendship Satisfaction: Renters consistently reported lower satisfaction with their broader friendships and community ties.
Sociologists note, however, that these variables are heavily confounded. Renters tend to be younger, earn lower median incomes, and move significantly more often—all independent risk factors for social isolation.
The Biological Cost of Housing Insecurity
Perhaps the most alarming finding in recent literature concerns cellular aging. A pioneering observational study of approximately 1,400 U.K. adults (Clair et al., 2024) analyzed DNA methylation—a reliable cellular biomarker of biological aging. The results startled researchers: private renters showed signs of looking biologically older than homeowners.
To put the scale of the effect into perspective, the accelerated aging associated with renting private accommodation was:
- Nearly twice the biological aging effect associated with being unemployed versus employed.
- 50 percent greater than the biological impact of being a smoker versus a lifelong non-smoker.
While the observational nature of the study means researchers cannot definitively prove that renting causes accelerated cellular aging, it underscores the intense chronic stress tied to housing arrangements.
Diving deeper into the root causes, a systematic review of 22 separate studies analyzing renter psychology (Talmatzky et al., 2026) revealed that housing instability—such as frequent, involuntary moves or the persistent threat of eviction—was explicitly linked to deteriorating mental health in 12 out of 14 studies. Additionally, high rent burdens directly correlated with worsened psychological well-being in six out of nine studies. The true villain, it appears, is not the act of renting itself, but the pervasive insecurity that accompanies it.
Official Responses and Expert Perspectives
As housing affordability dominates political discourse globally, urban planners, economists, and mental health professionals are weighing in on the systemic implications of a generation locked out of property ownership.
Government housing agencies and municipal leaders have faced mounting pressure to address supply constraints through zoning reforms, subsidies for first-time buyers, and enhanced tenant protection laws. In major metropolitan areas across the U.S., U.K., and European Union, policymakers are increasingly debating rent-stabilization frameworks aimed at mitigating the acute psychological distress caused by sudden, exorbitant rent hikes.
Meanwhile, consumer psychologists point out a deeper, symbolic relationship we hold with physical spaces. Drawing on classic research into access-based consumption—such as studies comparing car-sharing models to car ownership (Bardhi & Eckhardt, 2012)—experts suggest that humans form distinct psychological attachments to possessions they control outright. When individuals lease or rent, they often exhibit a reduced sense of responsibility and connection toward the asset.
However, housing advocates argue that this dynamic can be reframed. If society is transitioning toward a renter-majority future for younger demographics, public policy and urban design must evolve to ensure that rental housing does not equate to civic alienation. Experts advocate for the creation of "intentional communities," long-term leases that provide genuine security, and neighborhood infrastructure designed to foster belonging regardless of whether residents hold a mortgage or a lease agreement.
Implications: Finding Well-Being Beyond the Deed
The comprehensive body of research surrounding homeownership delivers a split verdict. On one hand, owning a home offers undeniable psychological dividends: greater pride in one’s living space, fortified neighborhood bonds, reduced loneliness, and—when managed without crippling debt—a powerful forced-savings mechanism that yields a valuable generational asset.
Yet, the core psychological benefits traditionally credited to homeownership are fundamentally rooted in stability. It is the psychological comfort of knowing you can stay put, put down deep roots, and avoid the existential dread of next year’s rent increase that truly drives well-being.
This realization offers a powerful blueprint of hope for the millions of renters who feel priced out of the traditional housing market. Stability is not exclusively reserved for those who hold a deed. Renters can actively cultivate many of the same psychological benefits by taking intentional steps:
- Commit to Place: When possible, choose to stay in one neighborhood or apartment longer to build genuine familiarity with your surroundings.
- Invest in Community: Make a deliberate effort to introduce yourself to neighbors, support local businesses, and participate in community groups.
- Create Sanctuary: Treat a rented space with the same emotional investment and care as a purchased home, personalizing it to foster a deep sense of psychological safety.
Ultimately, while paying off a mortgage remains a critical financial engine for wealth accumulation, the cultural obsession with property ownership can sometimes obscure what truly matters. Psychological research consistently demonstrates that doing meaningful work, maintaining physical health, and nurturing rich, supportive social circles with friends and family are infinitely more powerful determinants of a happy, fulfilling life than the legal structure of your housing arrangement.
References
- Bardhi, F., & Eckhardt, G. M. (2012). Access-based consumption: The case of car sharing. Journal of Consumer Research, 39(4), 881–898. https://doi.org/10.1086/666376
- Belonging Forum. (2024, March 22). Renters feel more lonely, unsafe, and unconnected to their local area—Groundbreaking 10,000-person poll reveals.
- Clair, A., Baker, E., & Kumari, M. (2024). Are housing circumstances associated with faster epigenetic ageing? Journal of Epidemiology & Community Health, 78(1), 40–46. https://doi.org/10.1136/jech-2023-220523
- Clark, A. E., & Diaz-Serrano, L. (2021). The long-run effects of housing on well-being (PSE Working Papers No. halshs-03230851). HAL.
- Clark, W. A. V., Ong ViforJ, R., Smith, S. J., Wood, G. A., Khuong Truong, N. T., & Lisowski, W. (2025). Wellbeing at the edges of ownership: The impacts of housing tenure, social capital, and institutions. International Regional Science Review, 48(4), 339–370. https://doi.org/10.1177/01600176241291140
- National Association of REALTORS. (2025). 2025 profile of home buyers and sellers. National Association of REALTORS Research Group.
- Talmatzky, M., Nohr, L., Knaevelsrud, C., & Niemeyer, H. (2026). Exploring the association between housing insecurity and mental health among renters: A systematic review of quantitative primary and secondary studies. PLOS ONE, 21(1), e0294222. https://doi.org/10.1371/journal.pone.0294222
- Will, S., & Renz, T. (2025). In debt but still happy? Homeownership and the satisfactions with housing and life. Journal of Housing Research, 34(1), 29–59. https://doi.org/10.1080/10527001.2024.2367279